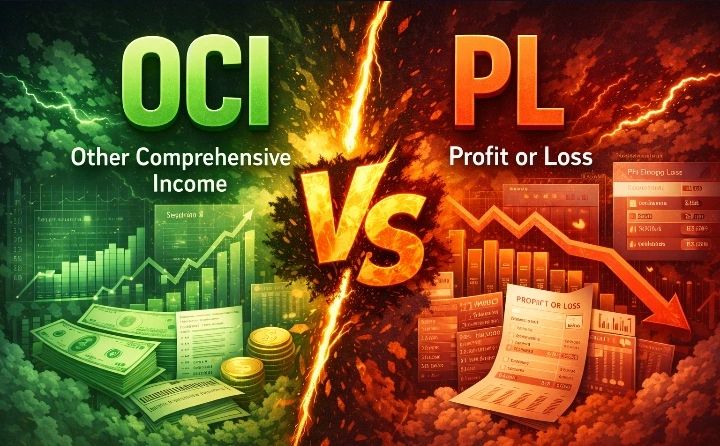
The structural integrity of financial reporting relies on the distinction between an entity’s current performance and specific technical adjustments to equity.
Profit or Loss (P/L) serves as the primary record for performance, while Other Comprehensive Income (OCI) is strictly reserved for “exceptions”—items that affect equity but are not part of day-to-day results. A frequent misconception is that all unrealized gains and losses belong in OCI; however, OCI only captures specific items mandated by international standards. These